🔍 Read the full analysis: US Growth And AI: Separating What The Data Says From What It Doesn’t on ThorstenMeyerAI.com

Get business pricing on tech for your team
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
TL;DR
US economic output and productivity have grown faster than hours worked, while job gains have been concentrated in a few sectors and real private-sector wages fell over the year to September. The figures show a stronger productivity trend, but they do not prove that AI caused it: business adoption remains limited and other explanations fit the data.
US output and productivity are rising faster than the hours people work, while job growth remains modest and uneven, according to government data through the third quarter of 2026. The figures have prompted questions about whether artificial intelligence is changing the labor market, but they do not establish that AI is the cause: only about one in four US businesses reported using AI in an early-October Census Bureau survey, and the employment pattern has other possible explanations.
The Bureau of Economic Analysis said real gross domestic product grew at a 3.4% annual rate in the third quarter, up from 2.2% in the second. Consumer spending, investment and government spending all contributed. The source article says computers and software accounted for about a third of the quarter’s growth, much of it tied to AI investment; that estimate describes spending and output contributions, not proof that AI has raised productivity across the economy.
For the nonfarm business sector, the Bureau of Labor Statistics reported that productivity rose 2.2% over the year to the second quarter of 2026. Output increased 2.5% during that period, while hours worked rose 0.2%. The source’s calculation from BLS indexes finds that from the fourth quarter of 2022 to the second quarter of 2026, output increased 10.0% and hours worked 0.9%, implying productivity growth of roughly 2.5% a year over that span.
The labor-market picture is less buoyant. Payrolls grew by 496,000 in the 12 months to September, with health care and social assistance adding 520,000 jobs. Information industries lost 120,000 jobs and remained 12% below their November 2022 peak. The source reports that real private-sector wages fell 0.6% over the year to September and that the labor share of business output reached 52.8% in the second quarter, its lowest level in the series dating to 1947.
Infographic 01 · More output, same hours
Ten percent more output, almost the same hours
The US business sector produces much more than three years ago with almost no extra work. The new jobs are mostly in health care.
The last 12 months
Nonfarm business sector, Q2 2025 to Q2 2026
- Outputreal, value added+2.5%
- Productivityoutput per hour+2.2%
- Hours workedall workers+0.2%
Where the jobs went
Payroll jobs, change over 12 months to Sep 2026 (preliminary)
Since Q4 2022: output +10.0%, hours +0.9%, productivity +9.1% (my arithmetic from the BLS indexes). Hiring rate in Aug 2026: 3.3% of jobs (2019 average 3.9%); layoff rate 1.0% (2019: 1.2%). Correlation, not proof of cause.
Sources: BLS, Productivity and Costs Q2 2026 (3 Sep 2026) · BLS, Employment Situation Sep 2026 · BLS, JOLTS Aug 2026.
Powered by Thorsten Meyer AI
Productivity Gains, Uneven Payoffs
The figures matter because productivity can support higher living standards over time, but the gains do not automatically reach workers as higher pay or more job opportunities. The source’s data show a gap between rising output and hours worked alongside a falling labor share and declining real private-sector wages. Those measures describe different parts of the economy, and the data alone do not establish why the gap has opened.
Job growth is also concentrated. Health care and social assistance added more jobs than the net payroll increase, while information-sector employment declined. That distribution can affect workers differently by industry and age. The source reports unemployment of 8.0% for people aged 20 to 24 and 7.0% for Black workers, compared with an overall rate of 4.2%. These are reported rates, not evidence that AI caused the disparities.
For businesses and policymakers, the distinction between an observed productivity increase and an AI-driven one is consequential. If AI is raising output per hour, the effects could shape investment, hiring and training decisions. But attributing economy-wide shifts to the technology without stronger evidence risks mistaking correlation for cause.
Products Worth Considering
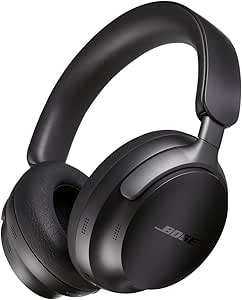
Bose QuietComfort Ultra Wireless Noise-Cancelling Headphones with Spatial Audio, Black

LG UltraGear 32GX850A-B 32-Inch 4K UHD Glossy OLED Gaming Monitor

Apple MacBook Air 13-inch with M5 chip, 16GB memory, 1TB SSD, and 12MP Center Stage camera (Midnight)
As an affiliate, we earn on qualifying purchases.
What the Productivity Measures Cover
Productivity is output divided by hours worked. The BLS measure cited in the source covers the nonfarm business sector: private businesses outside farming. It excludes government, nonprofits and households, so it is not a complete measure of every kind of work or activity in the economy.
The source compares annualized productivity growth of 2.1% from the end of 2019 through the second quarter of 2026 with 1.5% a year from 2007 to 2019. Those periods suggest a faster recent pace, but they do not isolate AI’s contribution. The launch of ChatGPT on November 30, 2022, is used as a convenient marker in the source’s comparison; a before-and-after calculation around that date cannot by itself identify the cause of a change.
The article also cites opinion coverage in the Financial Times on October 31 and a Wall Street Journal headline the following day about strong growth and uneven benefits. Its author says the full articles were inaccessible and bases the analysis instead on statistics from the BLS, BEA, Census Bureau, Federal Reserve and Eurostat. The cited official data are the basis for the figures here; interpretations about their causes remain separate.
The data cited do not measure how much of the productivity increase came from AI. The Census Bureau finding that about one in four businesses used AI in early October does not show how intensively those businesses used it, which tasks it affected, or whether it changed their output or staffing.
Other parts of the story complicate a simple AI explanation. The source says technology employment began shrinking before generative AI was widely used in businesses. It also notes that hiring is slow while layoffs remain low, a pattern that could reflect reduced recruitment rather than a wave of AI-related job cuts. The figures provided do not settle which forces account for the changes in output, hiring, wages or sector employment.
The comparisons also cover different periods and measures: GDP growth is reported for the third quarter, while the cited productivity figures run through the second quarter and payroll figures through September. The source does not provide enough detail to reconcile all measures into a single explanation. Nor does it establish whether the wage and labor-share movements will persist.
Upcoming Data to Watch
The next revisions and releases from the BEA and BLS can change the estimates for GDP, productivity, hours and employment. Readers should compare updated figures using the same sectors and time windows, rather than treating a quarterly estimate and a year-over-year measure as interchangeable.
Evidence about AI’s role will require more than economy-wide output and job totals. Business adoption measures, industry-level productivity, detailed hiring and wage trends, and information about which tasks are being automated or augmented could help clarify the link. Until those measures show a more direct connection, the responsible conclusion is limited: productivity has improved, labor-market gains are uneven, and AI remains one possible contributor rather than a demonstrated cause.
Key Questions
Did AI cause the recent rise in US productivity?
The cited data do not establish that. Productivity rose, but the available figures do not isolate AI’s contribution from other changes in technology, investment, demand or business practices.
How fast did US productivity grow?
The BLS figure cited by the source shows nonfarm business productivity rising 2.2% over the year to the second quarter of 2026. The source separately calculates roughly 2.5% annual growth from the fourth quarter of 2022 to the second quarter of 2026 using BLS indexes.
Were US businesses widely using AI?
About one in four businesses reported using AI in an early-October Census Bureau survey, according to the source. That figure does not indicate how extensively AI was used or what effect it had on output or employment.
Where were jobs added or lost?
In the 12 months to September, payrolls increased by 496,000. Health care and social assistance added 520,000 jobs, while information industries lost 120,000, according to figures cited in the source.
What is still unknown about workers’ share of growth?
The source reports a 52.8% labor share in the second quarter and a 0.6% year-over-year decline in real private-sector wages through September. The figures do not explain the causes or show whether these trends will continue.
Source: ThorstenMeyerAI.com